Rent is declared in the year the tenant pays it, and the costs of earning it are deductible, some in the same year and some over several years. A sale is measured from the contract date. Two of those rules change from 1 July 2027: negative gearing for residential investments is limited to new builds, and the 50% CGT discount is replaced by cost base indexation and a 30% minimum tax rate. The ATO says these measures are now law.
What this isThis is a guide to how the ATO taxes a residential rental property, written and published by Dotto. It is general information, not tax advice for anyone’s property or return, and its worked figures are illustrative. The ATO’s Rental properties 2026 guide is the place to check, and a registered tax agent can advise on a particular return.
Five dates the ATO sorts a rental by
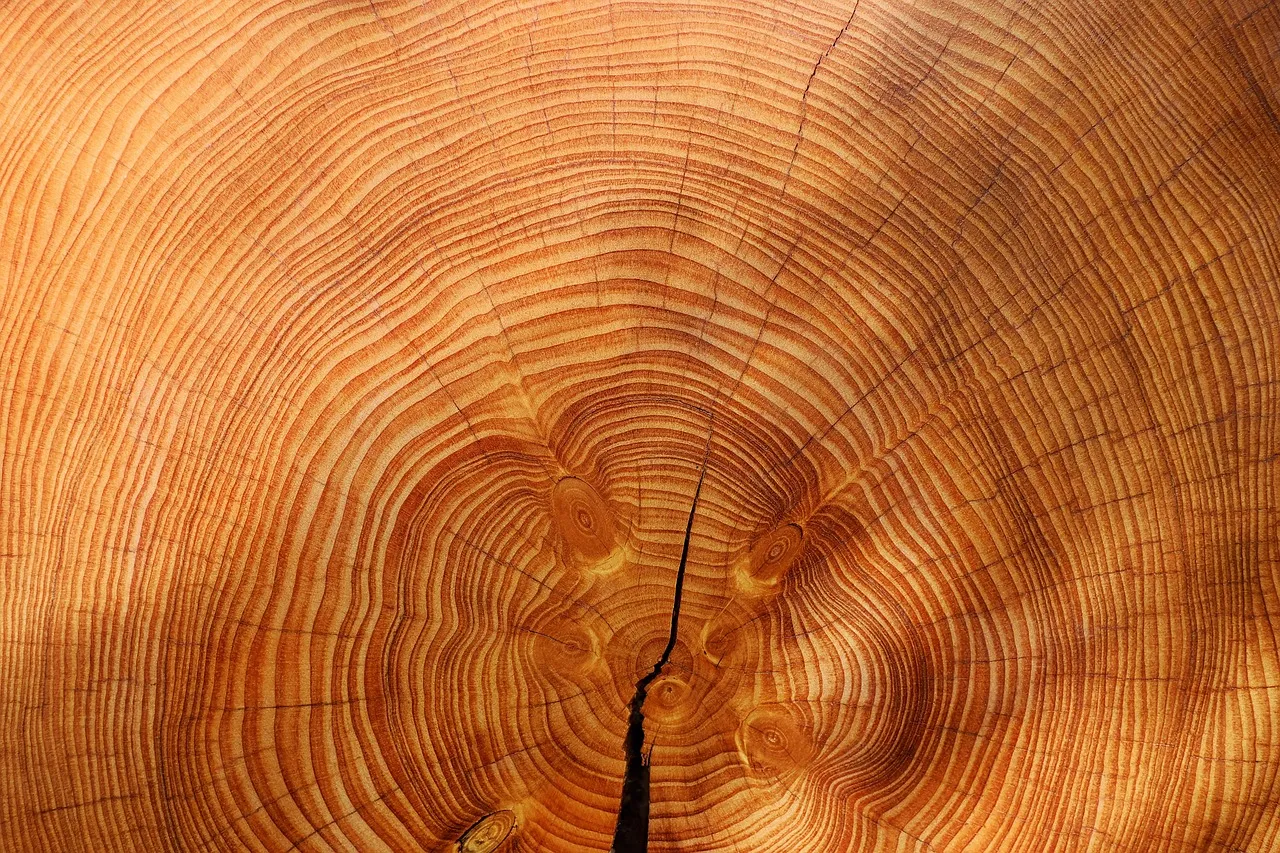
Read the drawing from the pith outwards, as a core sample is read. Each numbered ring is a date on which a rule about rental property begins or ends.
- 120 September 1985
Capital gains tax reaches the whole of a property acquired after this date. For one acquired before it, CGT applies only to certain capital improvements made after it.
- 221 September 1999
An asset owned since before this date can have its cost indexed for inflation instead of taking the CGT discount, though the ATO says the discount usually gives the smaller gain. The 50% discount itself dates from 1999.
- 31 July 2017
From this date, travel costs relating to a residential rental can’t be deducted, except by owners in the business of letting rental properties and what the ATO calls excluded entities.
- 412 May 2026, 7:30pm AEST
The Budget announcement of the negative gearing and CGT reform. Properties held at that moment are exempt from the negative gearing change.
- 51 July 2027
The reform applies: negative gearing for residential investments limited to new builds, and, for individuals, trusts and partnerships, the 50% CGT discount replaced for gains that accrue after this date, with a new build’s buyer able to choose either. In the drawing it is the dashed ring beyond the bark, the one still to grow.
The rule today, beside the rule from 1 July 2027
Today
When the expenses are more than the rent, the rental deductions can be claimed against rental and other income, such as salary, wages or business income.
An owner entitled to the CGT discount, which needs at least 12 months of ownership and Australian residency for tax purposes, first subtracts any capital losses from other assets and then reduces the gain that remains by 50%, or by 33.33% for a complying super fund; companies can’t use the discount.
From 1 July 2027
For an established residential property bought from 7:30pm AEST on 12 May 2026, losses can be set only against residential property income, including capital gains, with any excess carried forward. New builds can still be negatively geared.
For individuals, trusts and partnerships, gains that accrue after 1 July 2027 are taxed with cost base indexation and a 30% minimum tax rate instead of the 50% discount. A buyer of a new build can choose either on selling it.
What the ATO asks of anyone who rents out a property
Its own list says an owner needs to:
- keep records right from the start
- work out which expenses can be claimed as deductions
- work out whether tax instalments need to be paid during the year
- declare all rental-related income in the tax return
- consider capital gains tax if the property is sold.
The five guides
- Rental income: what counts, when, and whose it isRent, kept bonds, booking fees and insurance for lost rent; the year it belongs to; how co-owners split it; tax paid through the year.
- Interest and borrowing costs on a rental loanWhen loan interest is deductible, a loan used for two purposes, and the borrowing costs spread over five years.
- Repairs, maintenance or improvements: the ATO’s lineFive kinds of work and when each is claimed, the repairs that count as capital, and why an itemised invoice matters.
- Rental losses and negative gearing, now and from 1 July 2027The rule today, the test for a property held to earn rent, travel since 2017, and the change by purchase date.
- Selling a rental: capital gains tax and the 2027 changeThe contract date, the cost base in words, the 50% discount today, and how a gain is split at 1 July 2027.
What these pages leave out
The decline in value of fittings and the capital works deduction for the building have detailed rules and schedules of their own; these pages touch them only where another rule turns on them. They also leave aside a rental outside Australia, where the ATO says special rules apply to the expenses, and buyers who are foreign or temporary residents, who first need approval before they purchase.